OPINION: De-risking the global electric vehicle value chain build-out
Recent headlines would want you to believe that electric vehicles (EVs), which arguably are the greatest disruptors the industry has seen since its birth more than a century ago, are no longer growing. Headlines are now dominated by negative stories, suggesting that the transition to EVs will be slower than many expected.
However, the facts do not quite fully support these headlines. Global EV sales grew some 31% last year over 2022. More than 14 million EVs were sold worldwide in 2023, and China was in the lead followed by Europe and the US. By comparison, it took Toyota’s Prius, the first hybrid electric, more than a decade to reach one million sales globally.
In the US, industry has already made concrete private-sector investment announcements of more than $188 billion in EV technologies over the last 9 years. More than $50 billion supports battery manufacturing, EV infrastructure and retraining as a result of the Infrastructure Investment and Jobs Act, and another $369 billion is available via the Inflation Reduction Act(IRA) for economy-wide clean energy investments.
Yes, the EV transformation is difficult, and it may not move as quickly in the future as there are many obstacles that have not been fully addressed for the nascent and just over a decade old technology. High sticker prices and lack of infrastructure is often the most mentioned consumer concern. Prices are coming down fast and price parity with traditional, internal combustion powered vehicles is likely in the next few years. Beyond Tesla, who built its own charging network worldwide, availability and reliability for owners of EVs by other manufacturers, continues to be problematic. A fair portion of the investments are going into addressing the much-needed charging infrastructure.
But there are also significant obstacles that the industry faces, which often remain “behind the curtain” for the consumer. Developing an efficient and sustainable EV manufacturing value chain to meet the ballooning demand is a tricky proposition, rife with financial risk, political uncertainty, and logistical complexity. The International Finance Corporation (IFC), the private sector arm of the World Bank Group, plays a unique and vital role in developing economies where the new EV supply chain reaches into. On the one hand, it mitigates risks for investors while creating opportunities for those developing economies.
Because the bulk of critical materials essential for making EV batteries, as well as processing facilities, are concentrated in a handful of emerging economies, those countries will play an increasingly important role in the EV value chain of tomorrow.
Right now, three quarters of the world’s cobalt supply comes from the Democratic Republic of Congo; 70% of the world’s mined nickel supply from Indonesia and the Philippines; 32% of the lithium supply is from South America, and 17% of the phosphate comes from Morocco. An electric vehicle battery can contain anywhere from 290kg to 333kg of minerals, depending on the battery chemistry.
In an ideal world, pragmatic processing of critical minerals into battery materials, in or near the countries where the raw materials are sourced, makes the best financial and environmental sense. These materials range from the various metal hydroxides and sulphates to precursor cathode active materials (pCAM) used in battery cells.
Processing closer to where critical minerals are mined would reduce transport costs and transport-related emissions. These emerging economies also tend to have cheaper electricity, abundant renewable energy potential, less expensive labour, and though it might seem counter-intuitive, in many cases quicker permitting times compared to many developed markets. All of that represents a sustainable competitive advantage.
But investing in those markets comes with its own set of challenges. Political uncertainties, for example, raise a country’s risk profile and drive borrowing costs up, which can dissuade manufacturers from even considering an opportunity. There are also Environmental, Social and Governance (ESG) issues in some countries that don’t meet international standards. Finally, a lack of infrastructure, such as power, water supply, wastewater treatment, and logistics, often hinders investments in manufacturing operations.
Given its mandate to support the development of private industry in developing economies, IFC is not a traditional bank. The investment officers who drive its $70 billion debt and equity portfolio are supported by technical and industry experts from across the world, often with decades of experience in such markets, who provide pre-investment support, including technical assistance, project preparation advisory, project development funding, as well as technical and ESG expertise to help upskill the company in the developing economy.
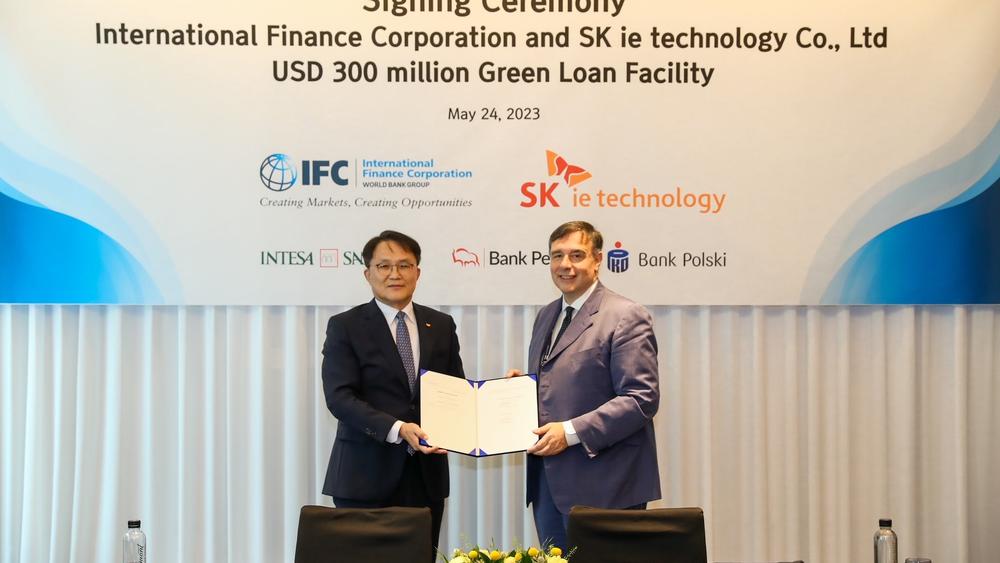
For example, IFC recently financed SK IE Technology with a green loan to produce battery separators in Poland. IFC also recently financed Allkem, a world-class lithium chemical producer, to support the development of Sal de Vida, a greenfield lithium operation in the province of Catamarca, Argentina.
The World Bank adds additional capability. Its new Resilient and Inclusive Supply-chain Enhancement (RISE) program will help emerging economies increase their participation in the manufacturing value chain of clean-energy products and boost their participation in the minerals industry.
Another part of the World Bank Group, the Multilateral Investment Guarantee Agency (MIGA), provides guarantees for cross border investments that cover non-commercial risks. When all these resources come together, they can help provide an umbrella of deterrence against government actions that could disrupt projects and assist in the resolution of disputes between investors and governments.
A transition to electric vehicles is essential if the world is to decarbonize the transport sector and limit the global temperature increase.
According to the International Energy Agency, “limiting the global temperature increase to below 2°C will require at least 20% of all road transport vehicles to be electrically driven by 2030 (approximately 300 million vehicles).”
With continued collaboration and support, the EV manufacturing value chain can thrive, contributing to a greener and more sustainable future. The IFC stands ready to be partner helping industry and developing economies stand up the new electro-mobility supply chain, and benefit from the transition.
Asogan Moodaly is Global Sector Lead for Automotive, Electronics and Machinery at the International Finance Corporation.
For more information about the service this data draws from, get in touch
Want to read more analytical content?
Create a Free Account
Create a free Intelligence account to access 3 content pieces per month.