Image for Middle East conflict set to push China needle coke prices to three-year high

Article | Nov 09, 2026 | 3 min read

Middle East conflict set to push China needle coke prices to three-year high

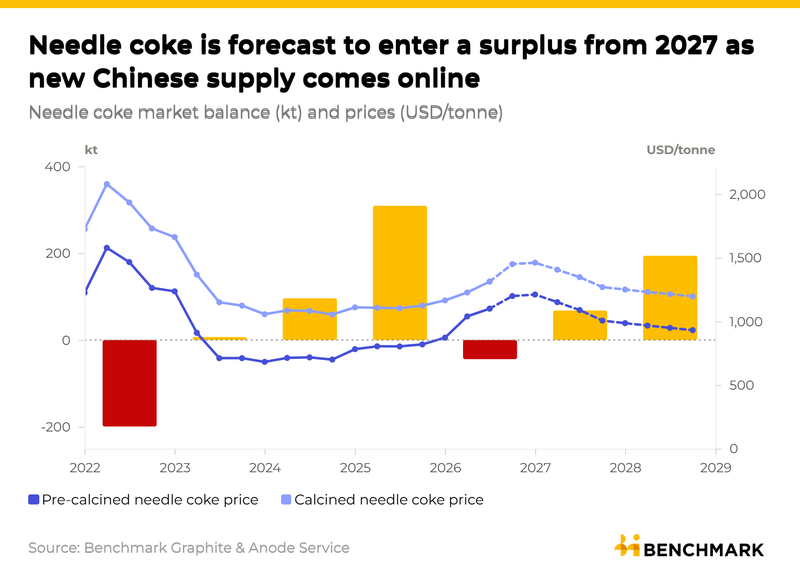
China needle coke prices are expected to rise sharply in Q4 2026, as escalating conflict in the Middle East pushes crude oil and slurry oil costs higher. Benchmark forecasts prices to peak in Q1 2027 at their highest level since early 2023, before easing as new supply in China comes online. Crude oil prices climbed through October as conflict in the Middle East intensified, with Houthi missile and drone attacks targeting Saudi energy infrastructure, including key Aramco facilities, raising the risk to regional oil supply. Brent oil prices stayed above $100/bbl throughout the month, peaking at around $117/bbl, before dipping to $90/bbl by 6 November. 

Image for GM–eVAC split highlights demand-side risk in US magnet buildout

Article | Oct 30, 2026 | 3 min read

GM–eVAC split highlights demand-side risk in US magnet buildout

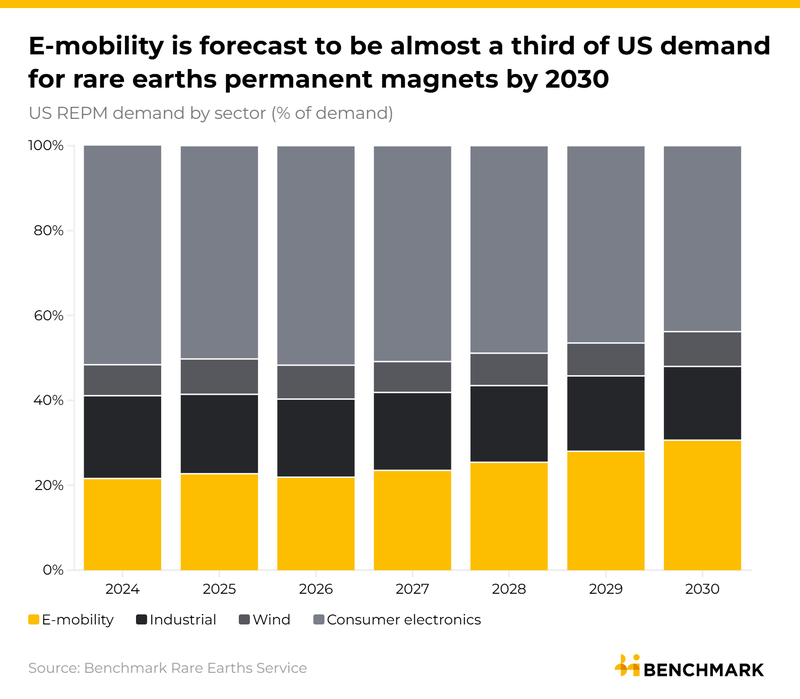
General Motors (GM) has cancelled its long-term rare earth permanent magnet (REPM) supply agreement with eVAC Magnetics, the US unit of Germany-based Vacuumschmelze (VAC), prompting an arbitration dispute. It comes following a 29% fall in US EV sales for GM in H1 2026 compared with H1 2025. Filings show a termination notice was issued on 1 July 2026, and eVAC began arbitration days later, alleging wrongful termination and seeking financial compensation. Signed in early 2023, this contract covered a minimum ten-year supply of neodymium-iron-boron (NdFeB) permanent magnets produced at the Sumter, South Carolina, plant with a capacity of 2,000tpa.

Image for What Australia's 2026 critical minerals update means for rare earths and lithium

Article | Oct 29, 2026 | 3 min read

What Australia's 2026 critical minerals update means for rare earths and lithium

Australia has given greater priority to national security and economic resilience in an update to its critical minerals strategy, a shift from a 2023 edition that placed heavier emphasis on climate goals. It also highlights the importance of international partnerships and targets government efforts where they can have the greatest comparative advantage by expanding domestic processing and refining. The 2026 update to the Critical Minerals Strategy 2023–2030 keeps the 2030 vision and six focus areas, but critical minerals, it says, "are no longer a resources issue". It announces no new money, restating existing commitments including the AUD 17.5 billion (USD 12.3 billion) Production Tax Incentive and a AUD 5 billion (USD 3.5 billion) Critical Minerals Facility. The update was discussed by Australian mining minister Madeline King at the International Mining and Resources Conference (IMARC) in Sydney on 27–29 October, where Benchmark lithium product director Cam Perks was in attendance.

Image for Lithium industry needs the equivalent of 134 new mines by 2050 to meet growing demand

Article | Oct 22, 2026 | 4 min read

Lithium industry needs the equivalent of 134 new mines by 2050 to meet growing demand

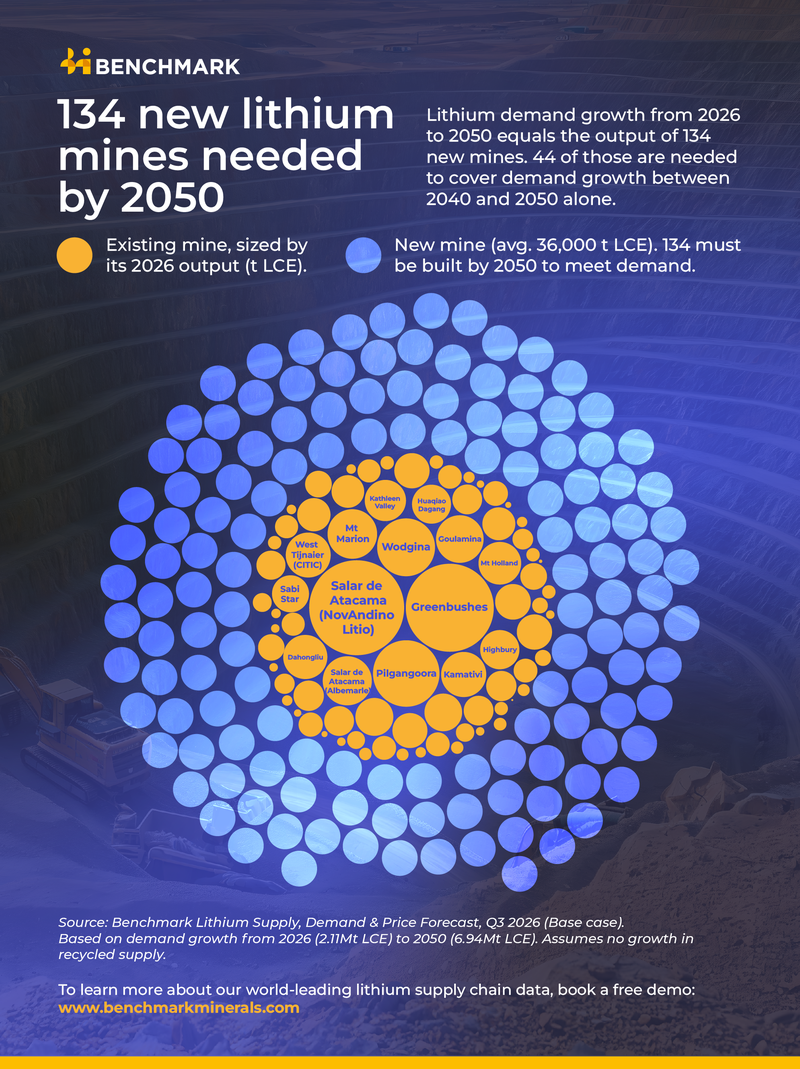
Between now and 2050, the lithium industry will need the equivalent of 134 new lithium mines to keep pace with rising demand for the critical mineral. Of these, 44 are needed to meet demand growth between 2040 and 2050 alone. Benchmark Mineral Intelligence forecasts that global lithium demand will reach ~7 million tonnes of lithium carbonate equivalent (LCE) in 2050, with 76% of this driven by electric vehicles. This is an increase of 4.8 million tonnes from a demand of 2.11 million tonnes LCE in 2026. At an average mine size of 36,000 tonnes LCE, this growth is equivalent to the output of 134 new mines – effectively a new mine every two months for the next 24 years.

Image for Recent US government capital driving America's graphite projects

Article | Oct 21, 2026 | 4 min read

Recent US government capital driving America's graphite projects

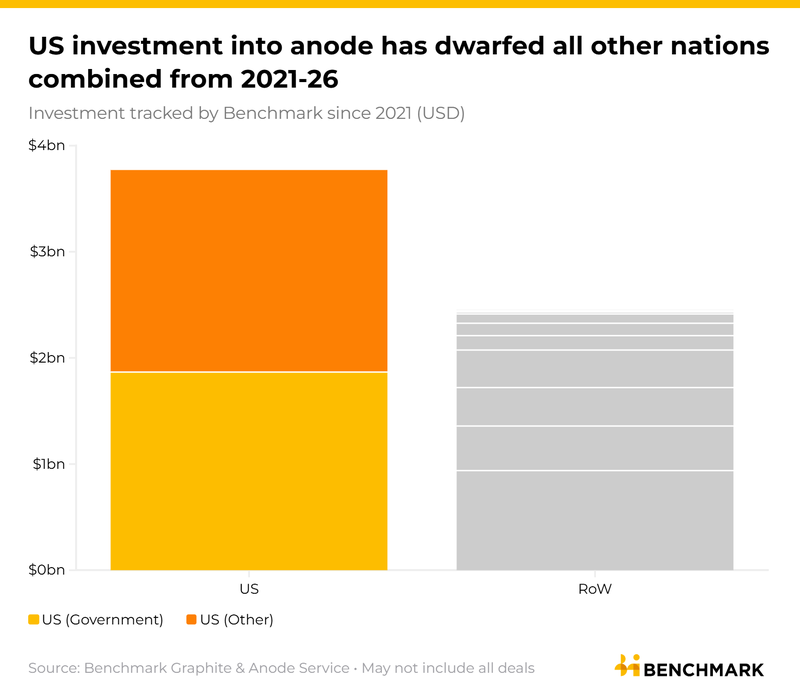
US federal agencies have emerged as major backers of the country’s graphite anode supply chain. Across August and September, the US Army and Export-Import Bank (EXIM) have provided funding or land for projects that have struggled to secure private investment. In August, EXIM approved a USD $25 million direct loan for Phase I of Westwater Resources' Kellyton, Alabama plant under its Make More in America Initiative. Phase I is designed to produce ~12.5ktpa of coated spherical purified graphite (CSPG). “Loans, land and grants are lowering the cost of building plants, and tariffs are closing most of the running-cost gap,” said Tony Alderson, Research Manager at Benchmark. “With buyers increasingly willing to pay for traceable, non-Chinese material, US projects are closer to competing than headline costs suggest.”

Image for South America mined lithium supply to grow 77% by 2040

Article | Oct 21, 2026 | 3 min read

South America mined lithium supply to grow 77% by 2040

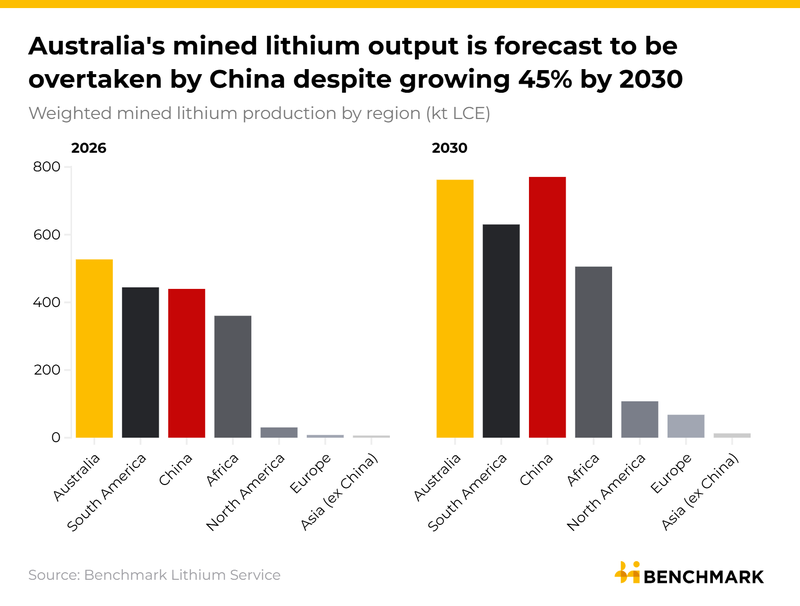
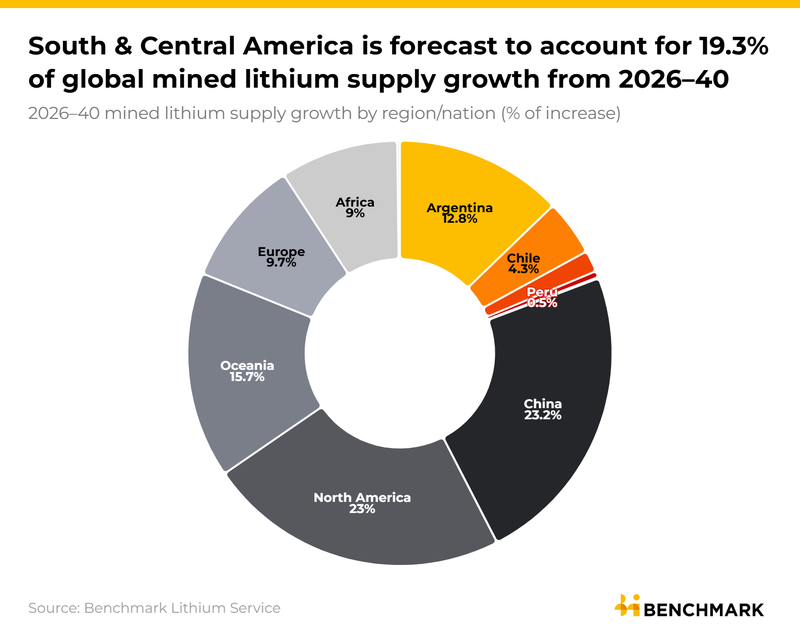
South America’s supply of mined lithium is expected to grow 77% from 2026 levels by 2040, according to Benchmark’s Lithium Service. The region is forecast to supply 444kt LCE in 2026 and 784kt in 2040. This growth is driven in large part by Argentina, which is expected to largely catch up with neighbouring Chile in lithium supply. Argentina’s supply is expected to increase by more than 200% over the period from 111kt to 337kt, while Chile is forecast to grow 25%, from 296kt to 371kt. "Argentina has become a beacon for lithium investment, driven by a combination of high-quality resources and a favourable investment framework, which has been critical in increasing companies' appetite for committing capital,” said Benchmark lithium analyst Federico Gay. “The country is bringing projects online quickly and still has a very attractive development pipeline."

Image for Can Cobre Panama copper mine run for 25 years without growing?

Article | Oct 06, 2026 | 3 min read

Can Cobre Panama copper mine run for 25 years without growing?

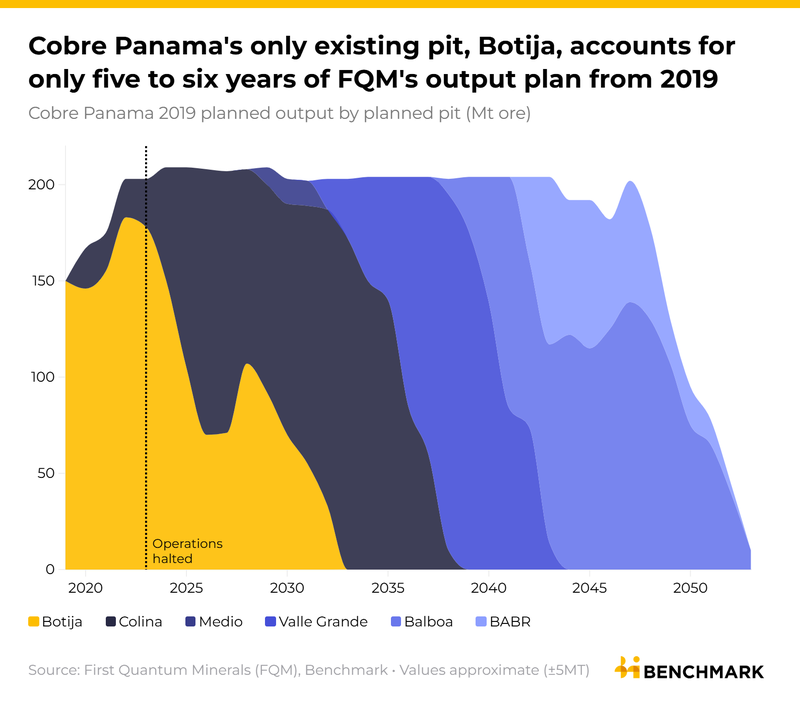
A commission convened by Panama’s government to decide how to manage the country’s controversial Cobre Panama copper mine has recommended 25 years of operation but without expanding the site’s physical footprint. The mine, run by First Quantum Minerals, was closed in 2023 after it was ruled unconstitutional following protests against its operation. The report also recommends steadily shrinking the existing footprint over this time, before eight years of “active closure” and 30 years of post-closure monitoring. Other non-negotiable criteria for reopening the site include compliance with existing Supreme Court rulings and laws around the project, ownership by the state, and the project must be financially self-sustaining. The report also calls for data transparency and supervision of the site to international standards, and priority given to concerns among affected Panamanian communities and businesses.

Image for Brazil’s EV charging network shifts into the fast lane

Article | Sep 30, 2026 | 2 min read

Brazil’s EV charging network shifts into the fast lane

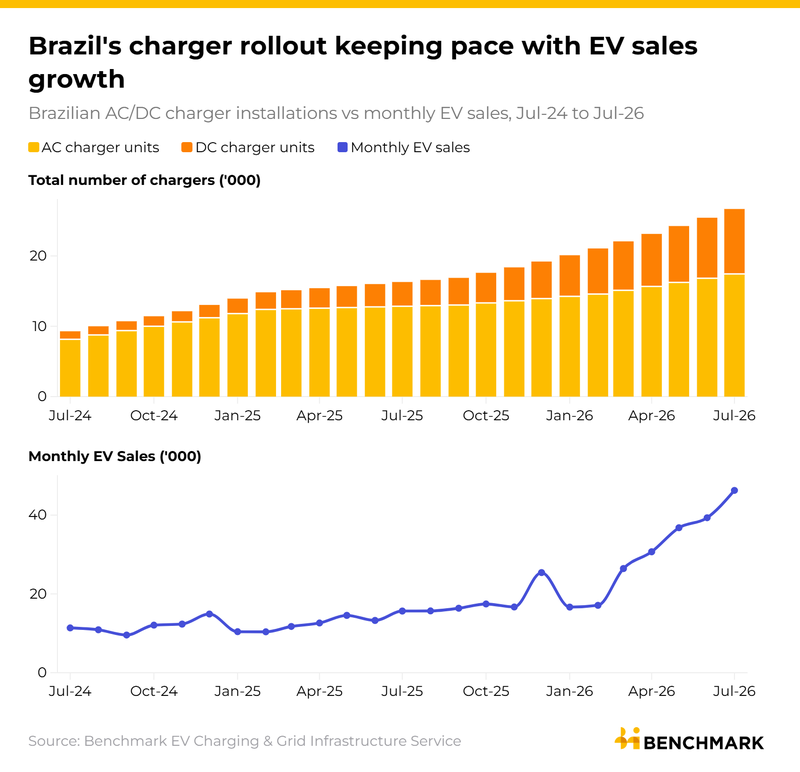
Brazil’s electric vehicle (EV) landscape is entering a new era of maturity thanks to growth in its charging network. What started as a handful of pilot projects has turned into a fast-growing, mature network built to meet the rapid growth in Brazil's EV demand. Recent data from Benchmark's EV Charging Service highlights a fundamental shift toward high-power, rapid-charging infrastructure capable of supporting both surging consumer adoption and heavy commercial logistics.

Image for Hydroxide standoff and broad decline: Q3 2026 Cobalt Price Review

Article | Sep 30, 2026 | 3 min read

Hydroxide standoff and broad decline: Q3 2026 Cobalt Price Review

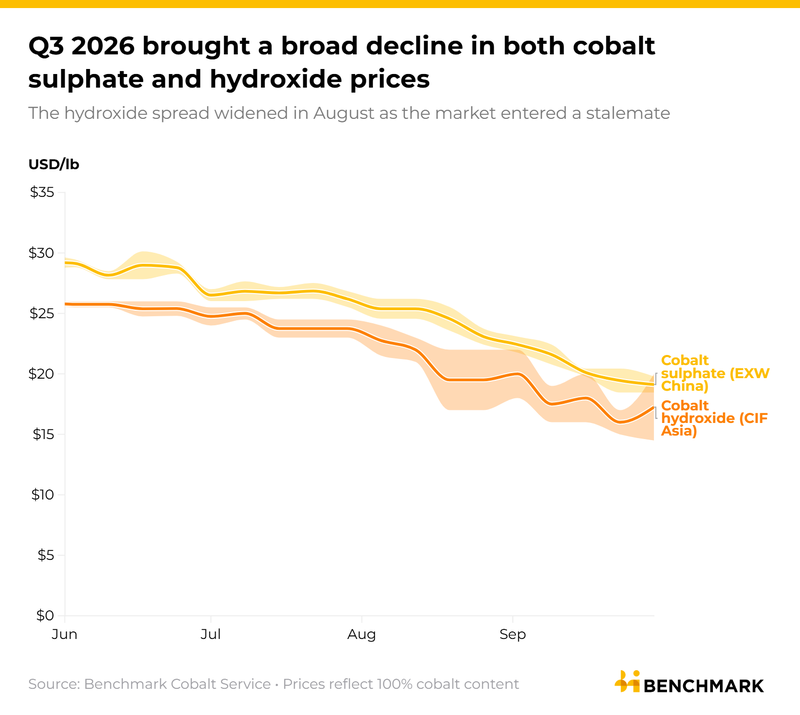
Increased DRC exports led to cobalt hydroxide prices (CIF Asia) falling 31% to across Q3 to $17.25/lb ($38,030/tonne), while cobalt sulphate prices (EXW China) dropped nearly 30% to RMB 58,000/tonne ($8,642), according to Benchmark’s Cobalt Price Assessment. EXW Europe cobalt metal prices eased about 11%, while CIF Asia MHP cobalt payables sank from 91.5% to 65.8% by mid September as a result of cheaper hydroxide offering an alternative. “Q3 2026 has seen a broad decline in prices across the cobalt supply chain as rising DRC-origin supply succeeded the weak downstream buying that defined Q2,” said George Ingall, a senior cobalt price analyst at Benchmark.

Image for Export interventions and payables under pressure: Q3 2026 Black Mass Price Review

Article | Sep 28, 2026 | 5 min read

Export interventions and payables under pressure: Q3 2026 Black Mass Price Review

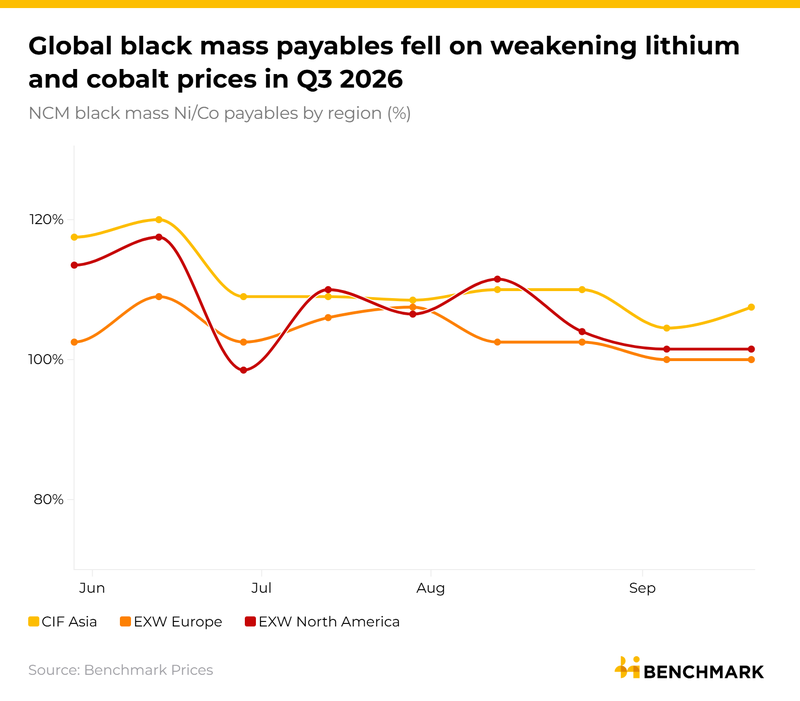
Benchmark’s NCM Black Mass EXW China payables have fallen 4.9% since the end of Q2, from 77.0% to 73.3%. Benchmark’s LCO Black Mass EXW China payables fell even more sharply, down 7.5% and 13.2% quarter-on-quarter for lithium carbonate and cobalt sulphate respectively, reaching 70.8% for both. Benchmark NCM Black Mass CIF Asia payables fell 10.4% q-o-q, from 120% to 107.5%, while Benchmark NCM Black Mass EXW North America and EXW Europe payables have dropped 13.6% and 8.3% respectively.

Image for Feedstock costs rise but AAM prices hold firm: Anode and Graphite Q3 2026 Price Review

Article | Sep 23, 2026 | 4 min read

Feedstock costs rise but AAM prices hold firm: Anode and Graphite Q3 2026 Price Review

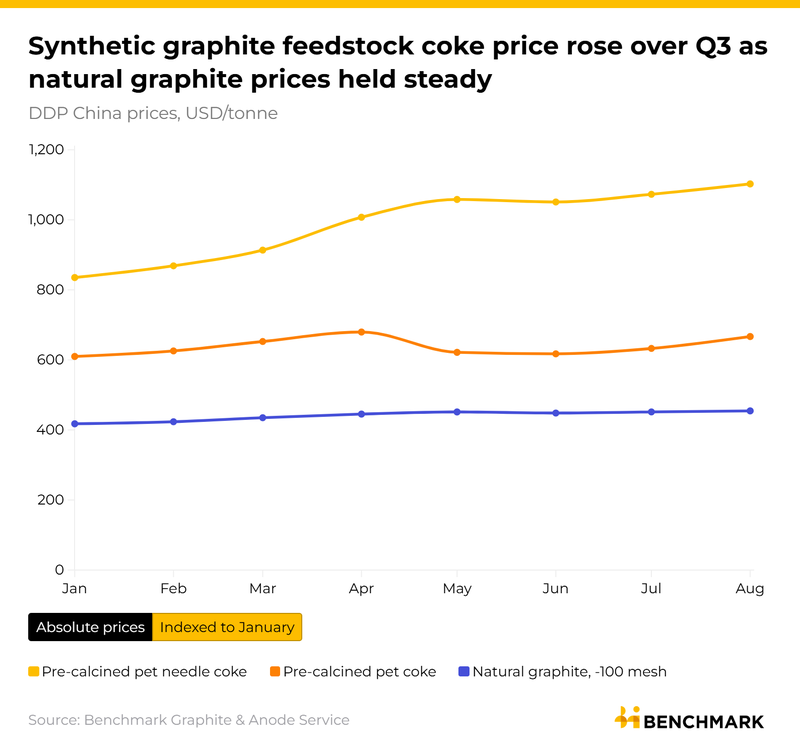
The divergence between natural and synthetic anode active material (AAM) prices observed earlier in the year stopped widening in Q3, with prices across both chemistries and all capacities remaining flat from mid-June- to mid-September. However, this midstream stability contrasted with continued movement in the feedstock markets during the same period, notably for coke materials, with pre-calcined pet coke prices rising 6.5% across July and August. “Q3 was characterised by a clear standoff between rising synthetic graphite feedstock costs and an oversupplied AAM market,” said Tony Alderson, anode and graphite research manager at Benchmark. “Producers absorbed the additional cost pressure rather than risk raising prices and losing market share. Meanwhile, coarser natural graphite flake grades continued to soften globally, whilst finer mesh material remained stable after reaching already depressed price lows from Q4 2025.”

Image for Uranium market entering a structural deficit as new demand drivers meet supply shortfall

Article | Sep 15, 2026 | 4 min read

Uranium market entering a structural deficit as new demand drivers meet supply shortfall

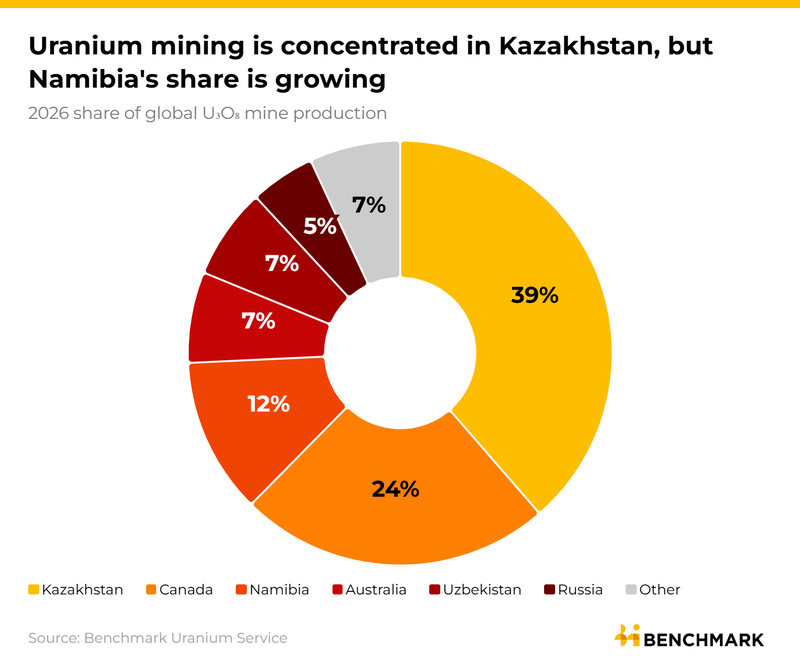
Following the 2011 Fukushima disaster, the uranium market and price environment remained muted, as reactor shutdowns vaporised demand faster than mine supply could adjust. Now, however, the uranium market is entering a structural deficit, as assessed by Benchmark's Uranium Service. The market is already in a marginal deficit for 2026. As nuclear power plays a growing role in the roll-out of data centres and other industries, this deficit is forecast to grow, and will continue to expand unless new supply can be brought online.